ContentIQ working paperCIQ-WP-2026-39CategoryVersion 12 Oct 2026
Books, Magazines & Audio on TikTok Shop is growing against a falling market, led by mid-priced products sold through video
339 videos tracked, 60 analysed in depth, 100 top-selling products, 3 Sept–2 Oct 2026
MediaLabs Research · in collaboration with Coherence Limited
Key findings
- 01+12.2%revenue in the latest 4 weeks against the previous 4
- 02+7.4% vs −11.1%13-week revenue change, category against the whole market
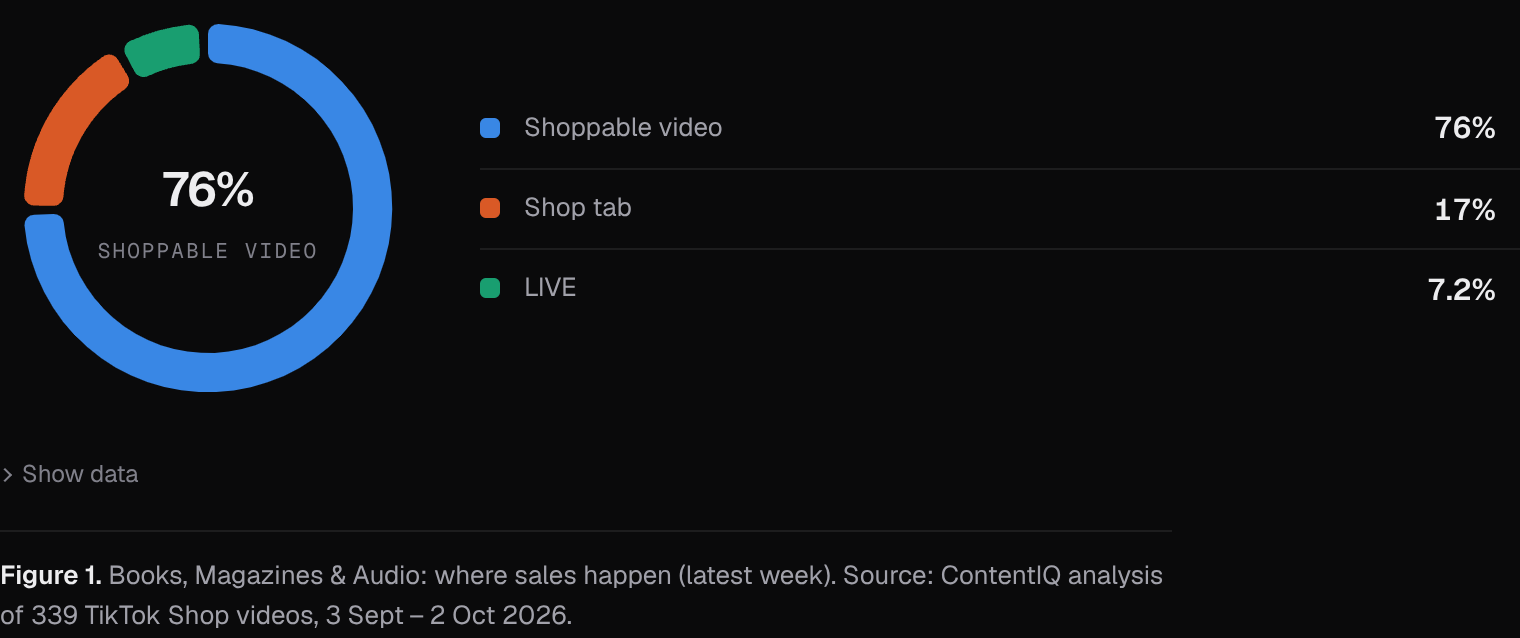
- 0376.3%of latest-week category revenue came through shoppable video, against 64.9% across the market
- 04$25revenue-weighted median price of top-selling products; the $20–35 band took 38.7% of revenue
- 051.3×sales per view for skits (90% range 1.0–1.8, 10 videos), the highest well-supported format
- 060.55AUC of the top-selling-video model (90% range 0.47–0.63), little better than chance
Contents
Abstract
We analysed Books, Magazines & Audio on TikTok Shop over 3 Sept–2 Oct 2026. The category's revenue in the latest 4 weeks was 12.2% above the previous 4, and its 13-week change was +7.4% while the market as a whole fell 11.1%. Sales run mainly through shoppable video (76.3% of latest-week revenue), and the top-selling products cluster around a revenue-weighted median price of $25 and a median commission of 12%. Among the 60 videos analysed in depth, no hook, format or production style separates clearly from the market average, and a model of top-selling videos ranks only slightly better than chance (AUC 0.55, 90% range 0.47–0.63).
1. Introduction
Brands and creators in books, magazines and audio must decide which products to put on TikTok Shop and what kind of video to make for them. The category is small in the market: it took 0.8% of tracked revenue in the latest 4 weeks and ranked 23rd of 28 categories. That raises a practical question: what sells here, and through which channel, price and commission?
Prior work shows that online attention is long-tailed and that early popularity predicts later popularity [1]. Recent short-video prediction work finds that creator features matter most, which limits what content features alone can explain [2]. Online booksellers sell a long tail of niche titles beyond the bestsellers [3], and live-stream selling is linked to trust and engagement in social commerce [4]. Affiliate commission rates are set by sellers for reasons that vary [5], and the returns to advertising are hard to measure from observational data [6].
This paper describes the category's momentum, channels, prices, commission, competition and seasonality, then asks which video openings, formats and production styles are associated with higher sales per view. All findings are associations, not effects.
2. Data
The window runs from 3 Sept to 2 Oct 2026. We tracked 339 videos in the category, and our AI analyst watched and analysed 60 of them in depth. The marketplace figures rest on the 100 top-selling products in the category. Market benchmarks, including the sales-per-view average of 1, draw on 3,625 videos analysed in depth across the wider market.
For each analysed video we recorded the hook, the format and the production style, along with its revenue and views. For products we recorded unit price, affiliate commission rate, launch date and sales channel. Category-level figures on momentum, shops and seasonality are estimates for the latest week, 29 Sept 2026, or for the past year.
Daily rankings of top-selling TikTok Shop videos in the US were collected from several independent sources and merged into one record per video. Where sources overlap, their sales estimates are cross-checked against each other, and videos whose estimates disagree by more than half are flagged. An AI analyst watched each video and recorded its opening, format, angle, production style, use of AI, hook source, length, pacing, what appears in the first second and how it is presented (people on screen, voice-over, setting, UGC or studio feel), without seeing how the video sold. Sales per view is a video group’s revenue per view divided by the market’s, shrunk toward the average for small groups, with 90% ranges. Weekly category figures for the US (estimated revenue, its split between video, LIVE and the shop tab, affiliate revenue, shops and active products, and a year of weekly revenue) and daily rankings of each category’s top-selling products (unit price, commission rate, launch date and revenue by channel) were collected from several independent sources. Medians of price and commission are weighted by revenue; momentum compares the latest weeks with the same number of weeks before. This paper covers 2026-09-03 to 2026-10-02: 339 videos tracked in Books, Magazines & Audio, 60 of them watched and analysed; the market baseline uses all 3,625 watched videos; 100 top-selling products in Books, Magazines & Audio. Predictions come from a logistic model retrained daily and tested on recent weeks it had not seen.
3. Methods
Sales per view is a group of videos' revenue per view divided by the market's, so 1 is the market average. Small groups are shrunk toward the average by empirical Bayes [7], and 90% intervals are computed on the log scale. A logistic model of top-selling videos is retrained daily and tested on recent weeks it had not seen. It is reported as AUC [8] with a bootstrap range [9].
Momentum compares the category's estimated revenue in the latest 4 and 13 weeks with the same number of weeks before. Channels split latest-week revenue into shoppable video, LIVE and the shop tab, plus the share credited to affiliate creators. Prices, commission rates and product age describe the tracked top-selling products. Medians and shares are revenue-weighted, and revenue per product is compared with the average product.
Competition is measured by shops and active products, average revenue per shop, the top ten products' share of top-product revenue and the Herfindahl–Hirschman index [10]. Seasonality compares each month's revenue with the category's average month over the past year, leaving out the partial first and last months. Separating season from trend follows [11].
4. Results: momentum, channels and competition
Revenue in the category in the latest 4 weeks was 12.2% above the previous 4 weeks. Over 13 weeks it rose 7.4% against the previous 13, while the whole market fell 11.1%. The category is still small, at 0.8% of market revenue.
Shoppable video carried 76.3% of latest-week revenue, the shop tab 16.5% and LIVE 7.2%. Across the market the split was 64.9%, 18% and 17.1%. So LIVE plays a much smaller role here than elsewhere. Affiliate creators were credited with 72.9% of the category's revenue.
The category has 2,181 shops and 12,817 active products. Average revenue per shop was $1,167, against $2,401 in the median category, which has 4,461 shops. The top ten tracked products held 32.2% of top-product revenue, equal to the median category, and the Herfindahl–Hirschman index among them was 188. Revenue is spread across many products rather than concentrated in a few.
5. Results: price, commission and product age
The revenue-weighted median price of the 100 top-selling products was $25, and the middle half sat between $19 and $35.82. The $20–35 band held 29 products and 38.7% of revenue, and its revenue per product was 1.34× the average product. The $10–20 band held the most products (37) and 29.5% of revenue, at 0.8× per product. Products at $60–100 (5 products) earned 0.5× the average and those at $100 and over (5 products) 0.64×, though both bands are thin.
The revenue-weighted median commission was 12%. The 10–15% band had the most revenue (44%, 33 products) at 1.09× per product. Products under 5% earned 1.63× per product, but there are only 4 of them, so we do not read much into it. In every commission band, 91% to 100% of product revenue was sold through video.
Products launched in the last 90 days produced 18.5% of top-product revenue. Products aged 1–2 years produced 29.7% (1.14× per product), and those over 2 years 10.8% (0.77×). These are descriptive patterns in a top-100 sample, and we cannot say that price or commission drives sales.
| Band | Products (n) | Share of revenue | Revenue per product vs average |
|---|---|---|---|
| Under $10 | 4 | 4.2% | 1.04× |
| $10–20 | 37 | 29.5% | 0.80× |
| $20–35 | 29 | 38.7% | 1.34× |
| $35–60 | 20 | 21.9% | 1.09× |
| $60–100 | 5 | 2.5% | 0.50× |
| $100 and over | 5 | 3.2% | 0.64× |
Note. Among the top-selling products we track in the latest week; revenue per product is against the average product in the same set (1.00 = average).
6. Results: openings, formats and production
Among 60 videos analysed in depth, differences are modest and most 90% ranges include 1. Skits had 1.34× the market's sales per view (range 0.996–1.79, 10 videos) and voice-over B-roll 1.31× (0.77–2.24, 6 videos, low confidence). Talking heads were at 0.92× (0.68–1.23) and demos or tutorials at 0.86× (0.63–1.17, low confidence). Talking heads took 28% of sales and slideshows 22.8%.
Bold-claim hooks, the most common opening with 13 videos, sold at 1.16× (0.88–1.53) and took 30.3% of sales. Relatable POV hooks were at 1.13× (0.74–1.72) and story openers at 0.94× (0.71–1.25). Photo slideshows (1.01×) and filmed live action (0.99×) were indistinguishable.
The model of top-selling videos reached an AUC of 0.55 (90% range 0.47–0.63), trained on 2,781 rows. It was not trained only on analyses that never saw sales (cleanOnly is false). The range includes 0.5, so the model is not reliably better than chance. Its largest odds ratios, before-and-after content (1.76) and boosting with ads (1.52), should be treated as hypotheses rather than findings.
| Value | Videos (n) | Share of sales | Sales per view | 90% range |
|---|---|---|---|---|
| Skit | 10 | 12% | 1.34× | 1.00–1.79 |
| Voice-over B-roll | 6 | 5.6% | 1.31× | 0.77–2.24 |
| Review or testimonial | 5 | 8.1% | 1.20× | 0.86–1.69 |
| Slideshow | 13 | 22.8% | 1.04× | 0.79–1.36 |
| Talking head | 10 | 28% | 0.92× | 0.68–1.23 |
| Demo or tutorial | 8 | 23.6% | 0.85× | 0.63–1.17 |
Note. Sales per view is relative to the market (1.00 = average), shrunk toward the average for small groups (empirical Bayes); ranges are 90% intervals on the log scale.
7. Discussion
For brands, the evidence points to products priced around $20–35, sold mainly through shoppable video with creator affiliates. The category is growing faster than the market, but average revenue per shop is about half that of the median category. That suggests a crowded field of small sellers, and standing out may matter more than the choice of format.
For creators, skits and voice-over B-roll sell at somewhat higher rates per view, and demos and talking heads somewhat lower. Intervals are wide and the sample is small, so this is a hypothesis to test, not a rule. The weak model agrees that format and hook alone say little about what becomes a top seller, which is consistent with the finding that creator features matter most in short-video prediction [2].
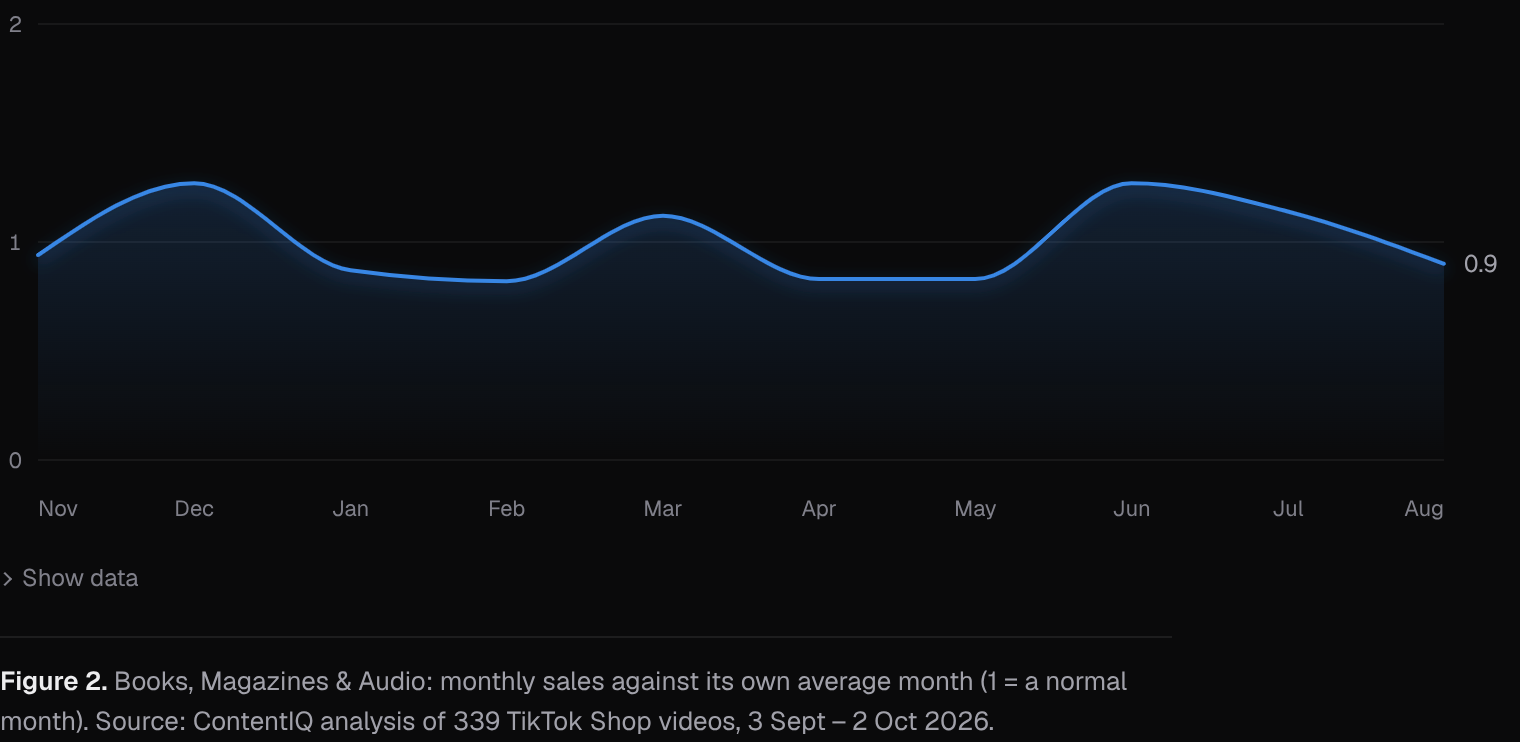
Over the past year, December and June were the strongest months (both 1.27× a normal month), followed by July (1.14×) and March (1.12×). January to February and April to May ran at 0.82–0.87×. Holiday gifting starts in 44 days and Black Friday / Cyber Monday in 39, and Halloween is already under way. This pattern rests on one year, so it could reflect individual events rather than a stable season. Other explanations for our results include creator reach, product quality, ad spend and title popularity, none of which we can separate here.
8. Conclusion
Books, Magazines & Audio is a small but growing category on TikTok Shop. Revenue is up 12.2% over 4 weeks and 7.4% over 13 weeks against a market down 11.1%, and it relies more on shoppable video (76.3%) and less on LIVE than the market. Top-selling products cluster around $25 with a 12% median commission, and revenue is spread across many shops and products.
Video-level differences are small and uncertain. Skits stand out most, at 1.3× sales per view with a range that just reaches 1.0, and the predictive model is only marginally above chance. Brands should test price points near $20–35 and creators should test skits and voice-over formats, while treating all of this as correlational and based on a limited sample.
Methodology
Daily rankings of top-selling TikTok Shop videos in the US were collected from several independent sources and merged into one record per video. Where sources overlap, their sales estimates are cross-checked against each other, and videos whose estimates disagree by more than half are flagged. An AI analyst watched each video and recorded its opening, format, angle, production style, use of AI, hook source, length, pacing, what appears in the first second and how it is presented (people on screen, voice-over, setting, UGC or studio feel), without seeing how the video sold. Sales per view is a video group’s revenue per view divided by the market’s, shrunk toward the average for small groups, with 90% ranges. Weekly category figures for the US (estimated revenue, its split between video, LIVE and the shop tab, affiliate revenue, shops and active products, and a year of weekly revenue) and daily rankings of each category’s top-selling products (unit price, commission rate, launch date and revenue by channel) were collected from several independent sources. Medians of price and commission are weighted by revenue; momentum compares the latest weeks with the same number of weeks before. This paper covers 2026-09-03 to 2026-10-02: 339 videos tracked in Books, Magazines & Audio, 60 of them watched and analysed; the market baseline uses all 3,625 watched videos; 100 top-selling products in Books, Magazines & Audio. Predictions come from a logistic model retrained daily and tested on recent weeks it had not seen.
Limitations
Most videos in the sample are top-ranked, so findings mostly separate strong sellers from good ones rather than from all videos; typical and weak videos are being added. Product figures cover the top-selling products we track in each category, not every listing, so they describe what sells best rather than everything on sale. Results are associations, not causes. Paid promotion, creator audience size and product price are not fully controlled for. Revenue, views and sales are estimates, not figures reported by TikTok. Only 60 videos were analysed in depth, and several groups have fewer than 10 videos or low confidence. The 100-product price, commission and age figures describe top sellers only, so they may not hold for the wider category. The seasonal pattern rests on a single year. The model's AUC range includes 0.5 and it was not trained only on analyses that never saw sales. The 4-week and 13-week changes are estimates from weekly revenue and can move with single products or promotions.
References
- [1]Szabo, G., & Huberman, B. A. (2010). Predicting the popularity of online content. Communications of the ACM, 53(8), 80–88. cacm.acm.org/research/predicting-the-popularity-of-online-content
- [2]Ye, L., Zhang, Y., Wu, Y., et al. (2025). MVP: Winning solution to SMP Challenge 2025 video track. arXiv:2507.00950. arxiv.org/abs/2507.00950
- [3]Brynjolfsson, E., Hu, Y. J., & Smith, M. D. (2003). Consumer surplus in the digital economy: Estimating the value of increased product variety at online booksellers. Management Science, 49(11), 1580–1596.
- [4]Wongkitrungrueng, A., & Assarut, N. (2020). The role of live streaming in building consumer trust and engagement with social commerce sellers. Journal of Business Research, 117, 543–556.
- [5]Libai, B., Biyalogorsky, E., & Gerstner, E. (2003). Setting referral fees in affiliate marketing. Journal of Service Research, 5(4), 303–315.
- [6]Lewis, R. A., & Rao, J. M. (2015). The unfavorable economics of measuring the returns to advertising. The Quarterly Journal of Economics, 130(4), 1941–1973.
- [7]Efron, B., & Morris, C. (1975). Data analysis using Stein’s estimator and its generalizations. Journal of the American Statistical Association, 70(350), 311–319.
- [8]Fawcett, T. (2006). An introduction to ROC analysis. Pattern Recognition Letters, 27(8), 861–874.
- [9]Efron, B., & Tibshirani, R. J. (1993). An Introduction to the Bootstrap. Chapman & Hall.
- [10]Rhoades, S. A. (1993). The Herfindahl–Hirschman index. Federal Reserve Bulletin, 79, 188–189.
- [11]Cleveland, R. B., Cleveland, W. S., McRae, J. E., & Terpenning, I. (1990). STL: A seasonal-trend decomposition procedure based on loess. Journal of Official Statistics, 6(1), 3–73.
Cite as
MediaLabs Research, in collaboration with Coherence Limited (2026). Books, Magazines & Audio on TikTok Shop is growing against a falling market, led by mid-priced products sold through video. ContentIQ Working Paper CIQ-WP-2026-39, version 1. https://medialabs-co.com/research/category-books-magazines-and-audio
Analysis and data: Coherence Research, Coherence ContentIQ. Published by MediaLabs in collaboration with Coherence Limited.
Version history
- Version 12 Oct 2026This version