ContentIQ working paperCIQ-WP-2026-25CategoryVersion 11 Oct 2026
Home Supplies on TikTok Shop: a recovering category with crowded shops, mid-priced products and bold-claim hooks that sell
785 videos tracked, 153 analysed in depth, 100 top-selling products, 1 category, 2 Sept–1 Oct 2026
MediaLabs Research · in collaboration with Coherence Limited
Key findings
- 01+14.4%revenue in the latest 4 weeks against the previous 4, while the 13-week view is -7.6%
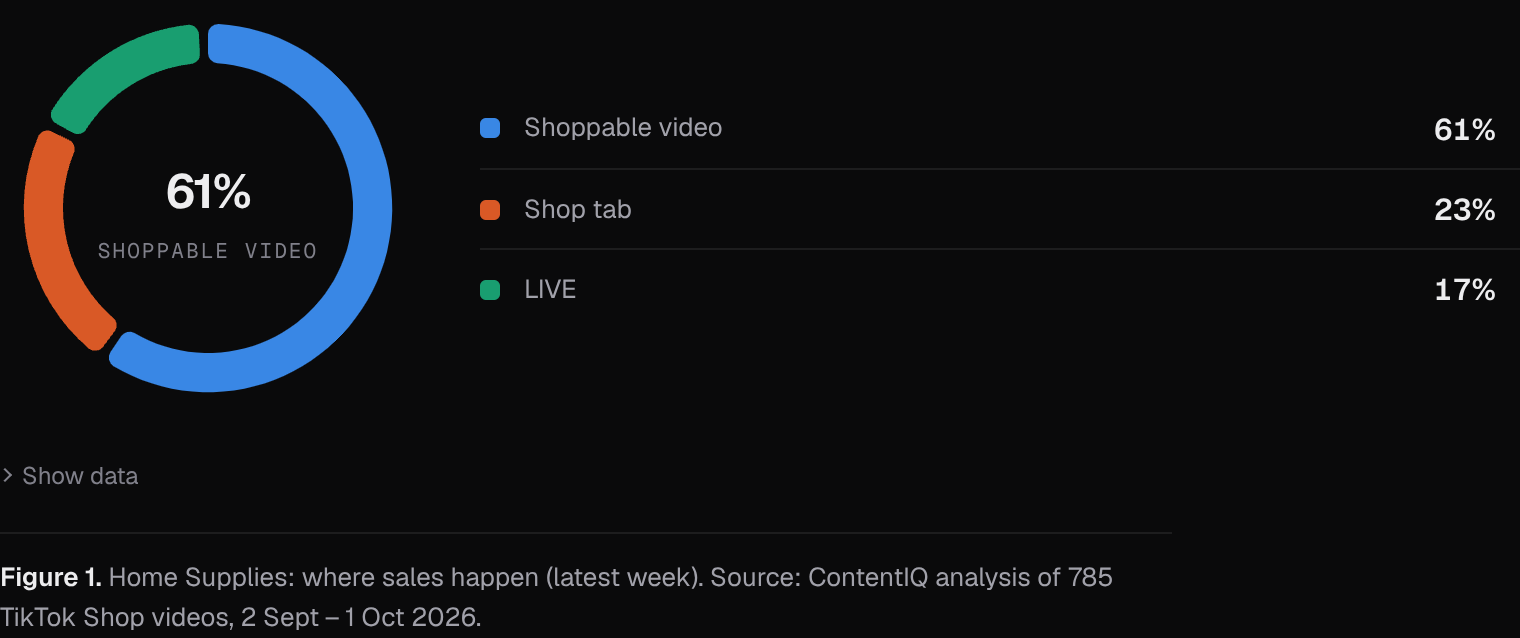
- 0261%of latest-week revenue came through shoppable video, with 16.5% from LIVE and 22.5% from the shop tab
- 03$25revenue-weighted median price of top products; the middle half sit between $16 and $37
- 0424%of top-product revenue came from products launched in the last 90 days
- 051.8×sales per view for bold-claim hooks versus the market (90% range 1.33–2.38, 15 videos)
- 06$1,106average revenue per shop, against $2,401 in the median category, across 17,599 shops
Contents
Abstract
We examine what sells in Home Supplies on TikTok Shop: momentum, sales channels, prices, commission, competition, seasonality and the video openings and formats associated with sales. Revenue in the latest four weeks was 14.4% above the previous four, though the 13-week comparison is still down 7.6% (the whole market is down 11.1%). Top sellers cluster at $20–35, and bold-claim openings sell at about 1.8× the market average per view (90% range 1.33–2.38). A model of top-selling videos separates winners only modestly (AUC 0.64, range 0.57–0.70), so the patterns are guides, not guarantees.
1. Introduction
Brands choosing what to list and creators choosing what to film in Home Supplies face two linked questions: is the category worth the effort, and what kind of product and video earns sales within it? Prior work shows that online attention is long-tailed and that early popularity predicts later popularity [1], and that short-video popularity models lean heavily on creator features [2] and on multimodal content signals [3]. Online retail also sells a long tail of niche products beyond the bestsellers [4], and live selling is linked to trust in social commerce [5].
Few public analyses connect category economics (price, commission, competition, season) with the creative choices that sit on top of them. We do so for one category, using a recent 30-day window. All findings describe associations, not causes.
2. Data
The window runs from 2 September to 1 October 2026. We tracked 785 videos in Home Supplies, and our AI analyst watched and analysed 153 of them in depth (a count of videos, not of views). Category-level figures rest on 100 top-selling products, and the category is compared with 28 ranked categories on TikTok Shop.
For each analysed video we recorded the hook, format and production style, along with the visible features used in the model. For the market we used weekly revenue over the past year, sales channels, unit prices, affiliate commission rates, product launch dates and counts of shops and active products, mostly as of the week to 29 September 2026.
Some video groups are small, so we flag confidence throughout. Counts differ slightly between hook, format and production tables because not every analysed video could be classified on every dimension.
Daily rankings of top-selling TikTok Shop videos in the US were collected from several independent sources and merged into one record per video. Where sources overlap, their sales estimates are cross-checked against each other, and videos whose estimates disagree by more than half are flagged. An AI analyst watched each video and recorded its opening, format, angle, production style, use of AI, hook source, length, pacing and what appears in the first second, without seeing how the video sold. Sales per view is a video group’s revenue per view divided by the market’s, shrunk toward the average for small groups, with 90% ranges. Weekly category figures for the US (estimated revenue, its split between video, LIVE and the shop tab, affiliate revenue, shops and active products, and a year of weekly revenue) and daily rankings of each category’s top-selling products (unit price, commission rate, launch date and revenue by channel) were collected from several independent sources. Medians of price and commission are weighted by revenue; momentum compares the latest weeks with the same number of weeks before. This paper covers 2026-09-02 to 2026-10-01: 785 videos tracked in Home Supplies, 153 of them watched and analysed; the market baseline uses all 3,342 watched videos; 100 top-selling products in Home Supplies. Predictions come from a logistic model retrained daily and tested on recent weeks it had not seen.
3. Methods
Sales per view is a group of videos' revenue per view divided by the market's, so 1 is the market average. Small groups are shrunk toward the average by empirical Bayes [6], and we report 90% intervals on the log scale. The predictive model is a logistic model of top-selling videos, retrained daily and tested on recent weeks it had not seen (time-split). We report AUC [7] with a bootstrap range [8].
Momentum compares the category's estimated revenue in the latest 4 and 13 weeks with the same number of weeks before, using weekly revenue over the past year. Channels split latest-week revenue into shoppable video, LIVE and the shop tab, plus the share credited to affiliate creators. Prices, commission rates and product age use the top-selling products tracked in the latest week. Medians and ranges are revenue-weighted, and revenue per product by band is set against the average product.
Competition counts shops and active products, average revenue per shop, and concentration among tracked top products as the top ten's share and the Herfindahl–Hirschman index [9]. Seasonality compares each month's revenue with the average month over the past year, leaving out partial months; separating season from trend follows [10].
4. Results: momentum, channels and competition
Home Supplies ranked 7th of 28 categories by revenue, with 5% of market revenue in the latest four weeks. Revenue in the latest four weeks was 14.4% above the previous four. Over 13 weeks it was 7.6% lower than the preceding 13, a milder fall than the market's 11.1%. The recent rise may therefore be a rebound within a softer quarter.
Shoppable video accounted for 61% of latest-week revenue, LIVE for 16.5% and the shop tab for 22.5%. The market splits 64.9%, 17.1% and 18%, so Home Supplies leans a little more on the shop tab. Affiliate creators were credited with 73.2% of category revenue.
The category is crowded: 17,599 shops and 91,427 active products. Average revenue per shop was $1,106, against $2,401 in the median category (4,461 shops). Among tracked top products the top ten took 30.9% of revenue, the same as the median category, with an HHI of 167. Revenue is spread across many products, not held by a few.
5. Results: price, commission and product age
The revenue-weighted median price of top products was $25, with the middle half between $16 and $37. The $20–35 band held 30 of the 100 products and 34.1% of revenue, and earned 1.14× the average product. The $35–60 band earned 1.09×. The $60–100 band (8 products) earned 0.65× and the under-$10 band (8 products) 0.93×. Several bands hold few products, so these ratios are indicative.
The revenue-weighted median commission was 9%. The 5–10% band (38 products) took 50.3% of revenue and the 10–15% band (28 products) 37.1%, both at 1.07× the average product. Products under 5% earned 0.67× and those at 15–20% earned 0.72×. The 20–30% band holds one product and should not be read as a pattern. Video's share of product revenue was about 80% for products under 10%, and 70.1% at 10–15%.
Products launched in the last 90 days produced 24% of top-product revenue. Those under 30 days earned 1.19× the average product, but those aged 30–90 days earned 0.61×. Older products held up, with 1.12× at 1–2 years and 1.24× beyond two years. New and established products can both reach the top, but the 30–90 day dip is not explained by our data.
| Band | Products (n) | Share of revenue | Revenue per product vs average |
|---|---|---|---|
| Under $10 | 8 | 7.4% | 0.93× |
| $10–20 | 28 | 26% | 0.93× |
| $20–35 | 30 | 34.1% | 1.14× |
| $35–60 | 17 | 18.5% | 1.09× |
| $60–100 | 8 | 5.2% | 0.65× |
| $100 and over | 9 | 8.8% | 0.98× |
Note. Among the top-selling products we track in the latest week; revenue per product is against the average product in the same set (1.00 = average).
6. Results: openings, formats and production that sell
Among analysed videos, bold-claim hooks sold at 1.78× the market per view (90% range 1.33–2.38; 15 videos, 7.3% of watched sales, medium confidence). Unboxing-reveal hooks showed a similar 1.79× (1.22–2.62), but on only 6 videos with low confidence. Relatable POV (36 videos, high confidence) sold at 1.22× (0.97–1.52). Problem call-outs (33 videos) held the largest share of sales, 35.3%, at 1.03× (0.80–1.32). Comparison hooks were lowest at 0.67× (0.47–0.94, low confidence).
By format, talking-head videos sold at 1.41× (1.07–1.86; 15 videos, medium confidence). Demos and tutorials were the largest group (74 videos, 45.5% of sales) at 1.00× (0.83–1.21). Slideshows sold at 0.80× (0.61–1.06). Filmed live action made up 94% of watched sales at 1.03× (0.89–1.20), and photo slideshows were 0.84× (0.63–1.11).
The model separated top-selling videos from others with an AUC of 0.64 (90% range 0.57–0.70), trained on 2,667 rows. It was not trained only on analyses that never saw sales (cleanOnly is false), so this figure may be flattered by that exposure. Filmed live action had the largest odds ratio (2.54), followed by a visual pattern-break paired with a review or testimonial (1.92). These are associations in a modest model.
| Value | Videos (n) | Share of sales | Sales per view | 90% range |
|---|---|---|---|---|
| Unboxing reveal | 6 | 2.4% | 1.79× | 1.22–2.62 |
| Bold claim | 15 | 7.3% | 1.78× | 1.33–2.38 |
| Relatable POV | 36 | 21.4% | 1.22× | 0.97–1.52 |
| Story opener | 9 | 9.4% | 1.07× | 0.77–1.48 |
| Problem call-out | 33 | 35.3% | 1.02× | 0.80–1.32 |
| Visual pattern-break | 9 | 5.7% | 0.99× | 0.65–1.52 |
| Straight into the demo | 12 | 7.1% | 0.91× | 0.69–1.21 |
| Question | 7 | 3.5% | 0.85× | 0.51–1.42 |
| Trend or sound | 12 | 5.5% | 0.82× | 0.62–1.09 |
| Comparison | 5 | 2.3% | 0.67× | 0.47–0.94 |
Note. Sales per view is relative to the market (1.00 = average), shrunk toward the average for small groups (empirical Bayes); ranges are 90% intervals on the log scale.
7. Discussion
For brands, Home Supplies offers demand and a rebound, but also heavy competition and low revenue per shop. The evidence points to the $20–35 band, where revenue per product was highest, and to commissions of 5–10% and 10–15%, where products earned 1.07× the average. Whether higher commission would buy more reach is not something these data can show; commission setting is a design choice with trade-offs [11]. Price points just below round numbers may also matter [12], though we did not test that.
For creators, bold claims and talking-head formats were associated with more sales per view, but their groups are small, and the intervals for most hooks and formats include 1. Demos and problem call-outs account for the bulk of sales, so the safest reading is that clear, filmed, live-action videos are the base and a strong claim or personal delivery is a promising variation to test. Alternative explanations include creator reach and product quality, and paid boosting (the model gave it an odds ratio of 1.59). Returns to advertising are hard to measure from observational data [13].
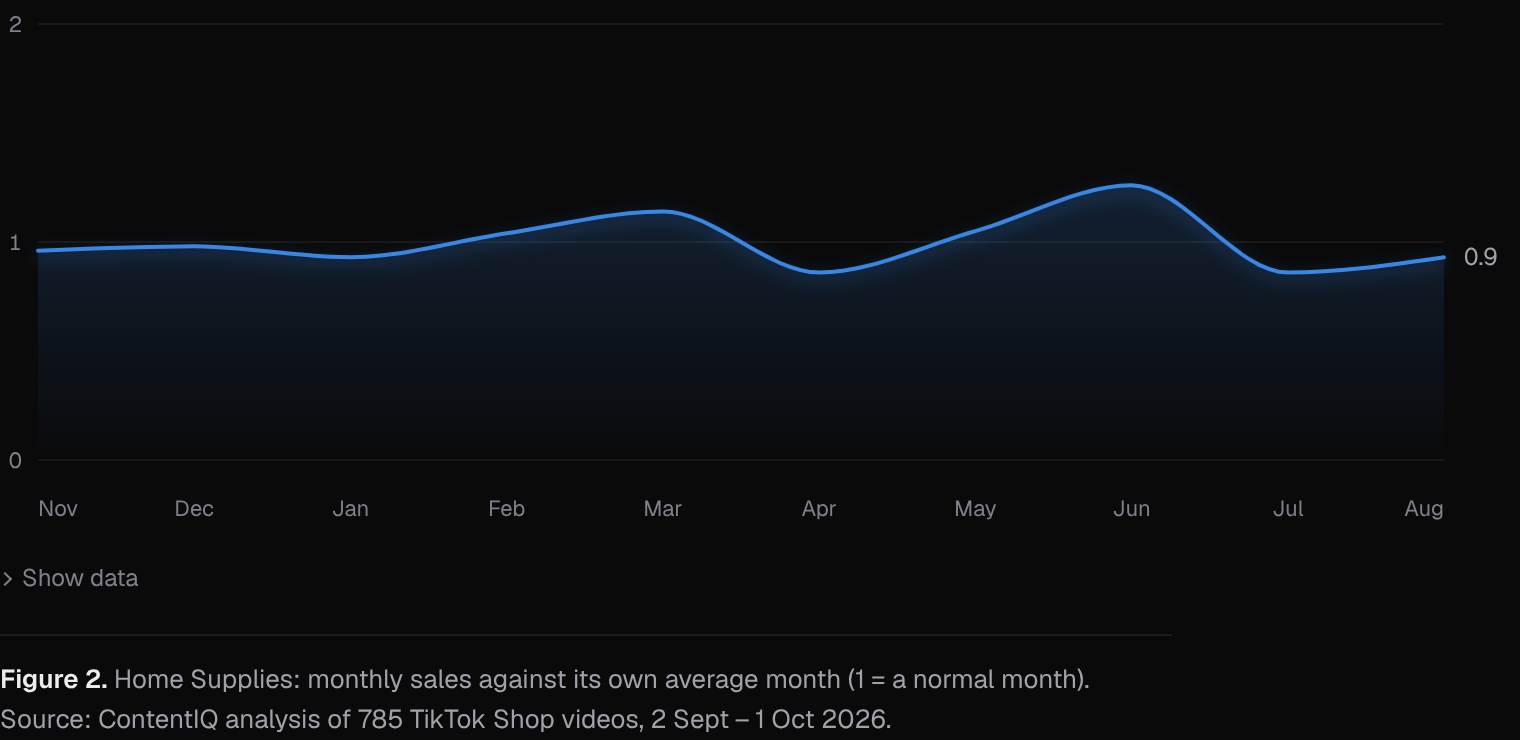
Seasonally, monthly revenue over the past year ranged from 0.86× to 1.26× a normal month. June was highest (1.26×) and March next (1.14×). November (0.96×) and December (0.98×) last year were near normal, so the category does not show a clear holiday peak. Halloween is under way, Black Friday / Cyber Monday starts in 40 days, holiday gifting in 45 days and New Year resolutions in 92 days. With one year of history, we cannot confirm that the pattern will repeat.
8. Conclusion
Home Supplies on TikTok Shop is a large, fragmented and recovering category. It is selling a little more through the shop tab than the market overall, and its top products cluster around $25 with commissions near 9%. Bold-claim hooks and talking-head formats were associated with higher sales per view, but on small samples, with wide ranges.
The practical reading is to price in the $20–35 range, test claim-led openings in filmed live action and watch the late-year moments closely. The findings are associations from one 30-day window and a single year of seasonality, and should be re-tested as the category moves.
Methodology
Daily rankings of top-selling TikTok Shop videos in the US were collected from several independent sources and merged into one record per video. Where sources overlap, their sales estimates are cross-checked against each other, and videos whose estimates disagree by more than half are flagged. An AI analyst watched each video and recorded its opening, format, angle, production style, use of AI, hook source, length, pacing and what appears in the first second, without seeing how the video sold. Sales per view is a video group’s revenue per view divided by the market’s, shrunk toward the average for small groups, with 90% ranges. Weekly category figures for the US (estimated revenue, its split between video, LIVE and the shop tab, affiliate revenue, shops and active products, and a year of weekly revenue) and daily rankings of each category’s top-selling products (unit price, commission rate, launch date and revenue by channel) were collected from several independent sources. Medians of price and commission are weighted by revenue; momentum compares the latest weeks with the same number of weeks before. This paper covers 2026-09-02 to 2026-10-01: 785 videos tracked in Home Supplies, 153 of them watched and analysed; the market baseline uses all 3,342 watched videos; 100 top-selling products in Home Supplies. Predictions come from a logistic model retrained daily and tested on recent weeks it had not seen.
Limitations
Most videos in the sample are top-ranked, so findings mostly separate strong sellers from good ones rather than from all videos; typical and weak videos are being added. Product figures cover the top-selling products we track in each category, not every listing, so they describe what sells best rather than everything on sale. Results are associations, not causes. Paid promotion, creator audience size and product price are not fully controlled for. Revenue, views and sales are estimates, not figures reported by TikTok. The video analysis rests on 153 analysed videos, and several hook and format groups have fewer than 15 videos and low confidence. The model is modest (AUC 0.64) and was not restricted to analyses that never saw sales. Seasonal indices come from a single year, price and commission bands with few products are unstable, and all findings are associations, not causal effects.
References
- [1]Szabo, G., & Huberman, B. A. (2010). Predicting the popularity of online content. Communications of the ACM, 53(8), 80–88. cacm.acm.org/research/predicting-the-popularity-of-online-content
- [2]Ye, L., Zhang, Y., Wu, Y., et al. (2025). MVP: Winning solution to SMP Challenge 2025 video track. arXiv:2507.00950. arxiv.org/abs/2507.00950
- [3]Lu, J., Wang, W., Xiao, M., et al. (2024). M3TR: Temporal retrieval enhanced multi-modal micro-video popularity prediction. arXiv:2411.15455. arxiv.org/abs/2411.15455
- [4]Brynjolfsson, E., Hu, Y. J., & Smith, M. D. (2003). Consumer surplus in the digital economy: Estimating the value of increased product variety at online booksellers. Management Science, 49(11), 1580–1596.
- [5]Wongkitrungrueng, A., & Assarut, N. (2020). The role of live streaming in building consumer trust and engagement with social commerce sellers. Journal of Business Research, 117, 543–556.
- [6]Efron, B., & Morris, C. (1975). Data analysis using Stein’s estimator and its generalizations. Journal of the American Statistical Association, 70(350), 311–319.
- [7]Fawcett, T. (2006). An introduction to ROC analysis. Pattern Recognition Letters, 27(8), 861–874.
- [8]Efron, B., & Tibshirani, R. J. (1993). An Introduction to the Bootstrap. Chapman & Hall.
- [9]Rhoades, S. A. (1993). The Herfindahl–Hirschman index. Federal Reserve Bulletin, 79, 188–189.
- [10]Cleveland, R. B., Cleveland, W. S., McRae, J. E., & Terpenning, I. (1990). STL: A seasonal-trend decomposition procedure based on loess. Journal of Official Statistics, 6(1), 3–73.
- [11]Libai, B., Biyalogorsky, E., & Gerstner, E. (2003). Setting referral fees in affiliate marketing. Journal of Service Research, 5(4), 303–315.
- [12]Anderson, E. T., & Simester, D. I. (2003). Effects of $9 price endings on retail sales: Evidence from field experiments. Quantitative Marketing and Economics, 1(1), 93–110.
- [13]Lewis, R. A., & Rao, J. M. (2015). The unfavorable economics of measuring the returns to advertising. The Quarterly Journal of Economics, 130(4), 1941–1973.
Cite as
MediaLabs Research, in collaboration with Coherence Limited (2026). Home Supplies on TikTok Shop: a recovering category with crowded shops, mid-priced products and bold-claim hooks that sell. ContentIQ Working Paper CIQ-WP-2026-25, version 1. https://medialabs-co.com/research/category-home-supplies
Analysis and data: Coherence Research, Coherence ContentIQ. Published by MediaLabs in collaboration with Coherence Limited.
Version history
- Version 11 Oct 2026This version